
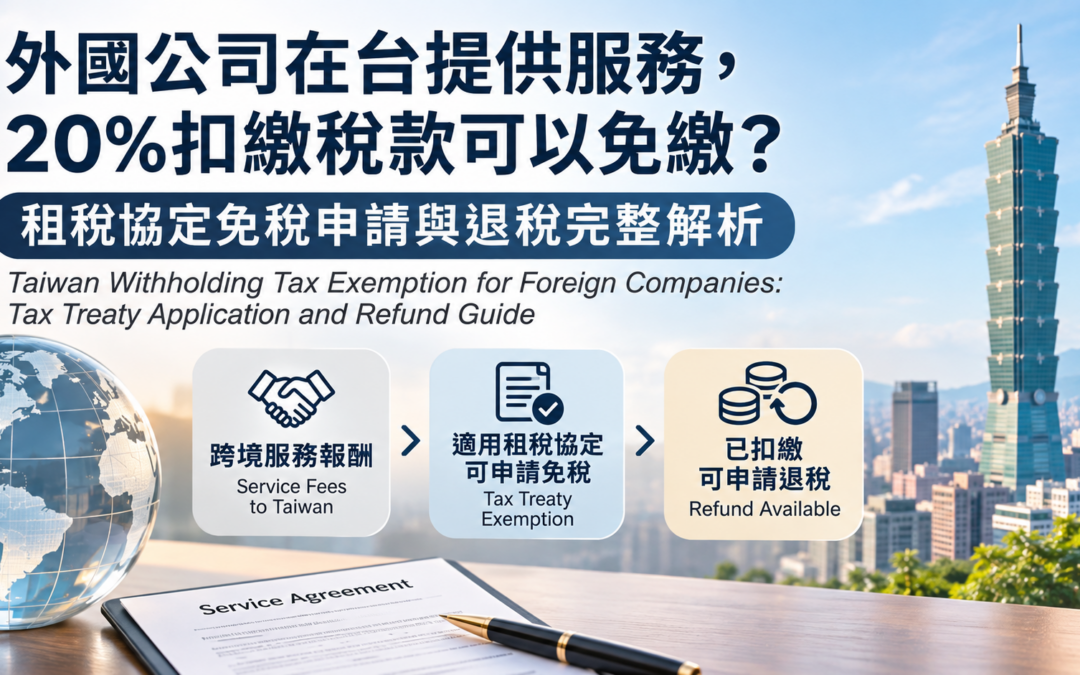
外國公司提供台灣企業技術顧問、管理諮詢、營業流程優化等專業服務,若派員來台提供勞務,相關服務報酬原則上屬於台灣來源所得,台灣企業付款時通常須扣繳20%所得稅。不過,如果外國公司所屬國家與台灣簽有租稅協定,且在台灣未構成常設機構等符合相關條件,就有機會申請免繳20%所得稅! 即使已經扣繳,也可能在取得國稅局核准後申請退稅。對於經常與外國企業合作的公司而言,事先了解租稅協定規定,有助於降低跨境交易的稅務成本。
When a foreign company provides technical consulting, management advisory, business process optimization, or other professional services to a Taiwanese company, income from services performed in Taiwan is generally subject to a 20% withholding tax. However, foreign companies from countries with a tax treaty with Taiwan may qualify for a withholding tax exemption if they do not have a permanent establishment in Taiwan and meet other applicable requirements. Even if the tax has already been withheld, a refund may be available after approval by the Taiwan tax authorities. Understanding these rules can help businesses reduce their cross-border tax costs.
一、為什麼外國公司服務費需要扣繳20%?
1. Why Are Payments to Foreign Service Providers Subject to 20% Withholding Tax?
依據台灣《所得稅法》第8條,外國公司在台灣境內提供勞務所取得的報酬,原則上屬於中華民國來源所得。
Under Article 8 of Taiwan’s Income Tax Act, income earned by a foreign company from services performed in Taiwan is generally considered Taiwan-sourced income.
因此,台灣企業支付相關服務費時,原則上應按20%的扣繳率扣繳所得稅,除非符合相關免稅或減免規定。
Therefore, Taiwanese companies are generally required to withhold 20% income tax when paying such service fees, unless an applicable exemption or tax reduction is available.
例如,台灣公司支付外國顧問公司新台幣100萬元的服務費,若適用20%扣繳率,應扣繳20萬元,外國公司實際收到80萬元。
For example, if a Taiwanese company pays NT$1 million in service fees to a foreign consulting firm, NT$200,000 would be withheld at the 20% rate, leaving the foreign company with NT$800,000.
但如果符合租稅協定免稅規定,並經國稅局核准,就可能免除這筆20%的扣繳稅款。
However, if the foreign company qualifies for a tax treaty exemption and receives approval from the tax authorities, the 20% withholding tax may be eliminated.
二、外國公司申請免稅,需要符合哪些條件?
2. Requirements for Foreign Companies to Qualify for a Tax Exemption
依財政部南區國稅局說明,截至2026年9月30日,台灣已有36個生效的全面性所得稅協定。
According to Taiwan’s National Taxation Bureau of the Southern Area, Taiwan had 36 comprehensive income tax treaties in force as of September 30, 2026.
外國公司若要申請適用租稅協定的營業利潤免稅規定,主要須符合以下條件:
To apply for an exemption under the business profits provisions of an applicable tax treaty, a foreign company generally needs to meet the following requirements:
1. 屬於租稅協定締約國的居住者
Be a tax resident of a country or jurisdiction that has an applicable income tax treaty with Taiwan.
2. 在台灣未構成常設機構(Permanent Establishment, PE)
Not have a permanent establishment (PE) in Taiwan under the applicable treaty.
3. 服務報酬符合租稅協定營業利潤條款
The service income must qualify as business profits under the relevant tax treaty provisions.
4. 依規定向國稅局提出申請並取得核准
Submit the required application and supporting documents to the Taiwan tax authorities and obtain approval.
特別注意,沒有在台灣設立分公司,不代表一定沒有常設機構,仍須依實際服務內容、營業場所及派員活動等情況判斷。
Importantly, not having a registered branch office in Taiwan does not automatically mean that a foreign company has no permanent establishment. The actual business activities, service arrangements, and physical presence must also be considered.
三、實際案例:日本公司來台服務45天,可申請免稅
3. Example: A Japanese Company Providing Services in Taiwan for 45 Days
日本A公司於2026年接受台灣甲公司委託,提供營業流程優化分析服務,合約報酬為1,000萬日圓。
In 2026, a Japanese company was engaged by a Taiwanese company to provide business process optimization and analysis services for a total fee of JPY 10 million.
日本A公司於2026年3月至6月間派遣人員來台提供服務,實際在台居留天數合計45天。
The Japanese company sent personnel to Taiwan between March and June 2026, with a total of 45 days of presence in Taiwan.
由於台灣與日本已有租稅協定,且該日本公司未在台灣構成常設機構,因此可申請適用臺日租稅協定的營業利潤免稅規定。
Because Taiwan and Japan have an applicable tax treaty, and the Japanese company did not have a permanent establishment in Taiwan, it could apply for a tax exemption under the business profits provisions of the Taiwan–Japan tax arrangement.
若在收到服務報酬前取得國稅局免稅核准,台灣公司即可依核准內容辦理免扣繳。
If the exemption is approved before payment, the Taiwanese company may make the payment without withholding the 20% tax, subject to the terms of the approval.
如果已經扣繳所得稅,也可於取得免稅核准函後,依規定申請退還已扣繳稅款。
If the tax has already been withheld, the foreign company may apply for a refund after obtaining the tax exemption approval.
四、租稅協定免稅申請流程與所需文件
4. Application Process and Required Documents
外國公司可以自行申請,也可以委託台灣會計師或代理人協助辦理。
Foreign companies may submit the application directly or appoint a Taiwan-based accountant or authorized representative to assist with the process.
申請流程通常包括確認租稅協定資格、準備必要文件、向國稅局提出申請,以及取得免稅核准函。
The process generally involves verifying tax treaty eligibility, preparing supporting documents, submitting the application to the tax authorities, and obtaining an exemption approval letter.
常見申請文件如下:
Commonly Required Documents:
| 中文文件 | English |
|---|---|
| 租稅協定營業利潤免稅申請書 | Tax Treaty Exemption Application Form |
| 外國稅務機關核發的居住者證明 | Certificate of Tax Residency |
| 雙方簽署的服務合約及必要譯本 | Service Agreement and Required Translation |
| 請款單、發票及服務證明 | Invoices and Supporting Service Records |
| 未構成常設機構的相關證明 | Evidence of No Permanent Establishment |
| 委託代理人的授權書 | Power of Attorney |
實際應提供的文件,仍須依服務內容及國稅局審查要求調整。
臺北國稅局+1
Additional documents may be required depending on the nature of the services and the reviewing tax authority’s requirements.
五、已經扣繳20%所得稅,還能申請退稅嗎?
5. Can Foreign Companies Claim a Refund of the 20% Withholding Tax?
可以!如果外國公司符合租稅協定免稅資格,即使台灣企業已經扣繳20%所得稅,仍可在取得國稅局免稅核准後,依規定申請退稅。
Yes. If a foreign company qualifies for a tax treaty exemption, it may apply for a refund of the 20% withholding tax already deducted, provided that the required exemption approval is obtained and the refund requirements are met.
例如,外國公司取得新台幣100萬元服務報酬,已被扣繳20萬元,若後續申請免稅成功,就有機會申請退還該筆20萬元稅款。
For example, if a foreign company receives NT$1 million in service income and NT$200,000 has been withheld, the company may be eligible for a refund of the NT$200,000 after successfully obtaining the tax treaty exemption.
因此,建議在簽訂跨國服務合約及付款前,就先確認免稅資格,避免後續增加退稅程序及行政成本。
Businesses are therefore encouraged to review their tax treaty eligibility before signing cross-border service agreements or making payments, reducing potential refund procedures and administrative costs.
六、常見問題 FAQ
6. Frequently Asked Questions
Q1:外國公司在台灣提供服務,一定要扣繳20%所得稅嗎?
Is a foreign company always subject to 20% withholding tax on service income earned in Taiwan?
不一定。若符合租稅協定免稅規定,並取得國稅局核准,即可能免除20%扣繳稅款。
Not necessarily. A foreign company may qualify for an exemption under an applicable tax treaty, subject to approval by the Taiwan tax authorities.
Q2:日本公司可以申請台灣20%扣繳稅款免稅嗎?
Can a Japanese company apply for Taiwan’s 20% withholding tax exemption?
可以申請,但須符合臺日租稅協定的相關條件,包括營業利潤及常設機構規定。
Yes, provided the company meets the relevant requirements under the Taiwan–Japan tax arrangement, including the business profits and permanent establishment provisions.
Q3:外國公司沒有在台灣設立分公司,就一定免稅嗎?
Does a foreign company automatically qualify for an exemption if it has no branch office in Taiwan?
不一定。是否構成常設機構,仍須依實際業務活動及適用租稅協定判斷。
No. Permanent establishment status depends on the company’s actual business activities and the provisions of the applicable tax treaty.
Q4:申請免稅需要提供居住者證明嗎?
Is a Certificate of Tax Residency required?
一般需要,通常應由外國公司所在地的稅務機關核發,以證明其符合租稅協定的居住者資格。
Generally, yes. A Certificate of Tax Residency issued by the foreign tax authority is typically required to establish eligibility for treaty benefits.
Q5:台灣公司可以協助外國公司申請免稅嗎?
Can a Taiwanese company apply for the exemption on behalf of a foreign company?
可以經外國公司授權,委託台灣公司、會計師或其他代理人協助申請。
Yes. A foreign company may authorize a Taiwanese company, accountant, or other representative to submit the application on its behalf.
Q6:已扣繳20%所得稅,可以申請退回嗎?
Can the 20% withholding tax be refunded after payment?
可以。符合免稅條件且取得國稅局核准後,可依規定辦理退稅。
Yes. If the foreign company meets the exemption requirements and receives approval, it may apply for a refund in accordance with the applicable rules.
Q7:外國公司沒有派人來台,仍需要扣繳20%嗎?
Is withholding tax required if the foreign company performs all services outside Taiwan?
不一定。須依服務提供地點、所得性質及相關法令判斷是否屬於台灣來源所得。
Not necessarily. The tax treatment depends on where the services are performed, the nature of the income, and whether the income is considered Taiwan-sourced under applicable tax laws.
Q8:取得免稅核准後,未來所有服務收入都可以免稅嗎?
Does an exemption approval cover all future service income?
不一定。若服務內容、合約條件或在台營業活動發生變更,可能需要重新評估免稅資格。
Not necessarily. Changes in service arrangements, contracts, or business activities in Taiwan may affect the company’s continued eligibility for the exemption.
七、理查會計師事務所|跨境稅務與租稅協定諮詢
7. Richar RichLife CPA | Cross-Border Tax and Tax Treaty Advisory Services
外國公司與台灣企業進行跨境交易時,應事先確認服務報酬是否涉及20%扣繳所得稅,以及是否符合租稅協定免稅條件,避免不必要的稅務負擔。
When conducting cross-border transactions with Taiwanese businesses, foreign companies should review potential 20% withholding tax obligations and available tax treaty exemptions to avoid unnecessary tax costs.
理查會計師事務所提供跨境稅務諮詢、外國營利事業扣繳評估及租稅協定相關申請協助,歡迎台灣企業及外國公司洽詢。
Richar RichLife CPA provides cross-border tax advisory services, withholding tax assessments, and assistance with tax treaty applications. We welcome inquiries from both Taiwanese businesses and foreign companies.
資料來源:國稅局